
Portfolios, not lucky symbols.
AurexionLabs is built for portfolios: many coins, chosen by a rule each day, and several portfolios on one account, tested together the way they would trade.
One symbol proves little.
A strategy tuned on one coin can look good by luck. Across many coins, and a rule that picks them the same way every day, the result has to hold up before you trust it.
Which coins, every day.
Pro and up
A good trading strategy on the wrong coins still loses. Choosing the coins is a strategy of its own, so AurexionLabs lets you build it, test it and run it like one.
Universes: the coins you are willing to trade
- A fixed list you choose, or a list built from a rule you write, for example every coin above a daily traded value over a past window.
- A coin sweep can write one for you: the coins where your strategy passed a significance test.
Selectors: which of them to trade today
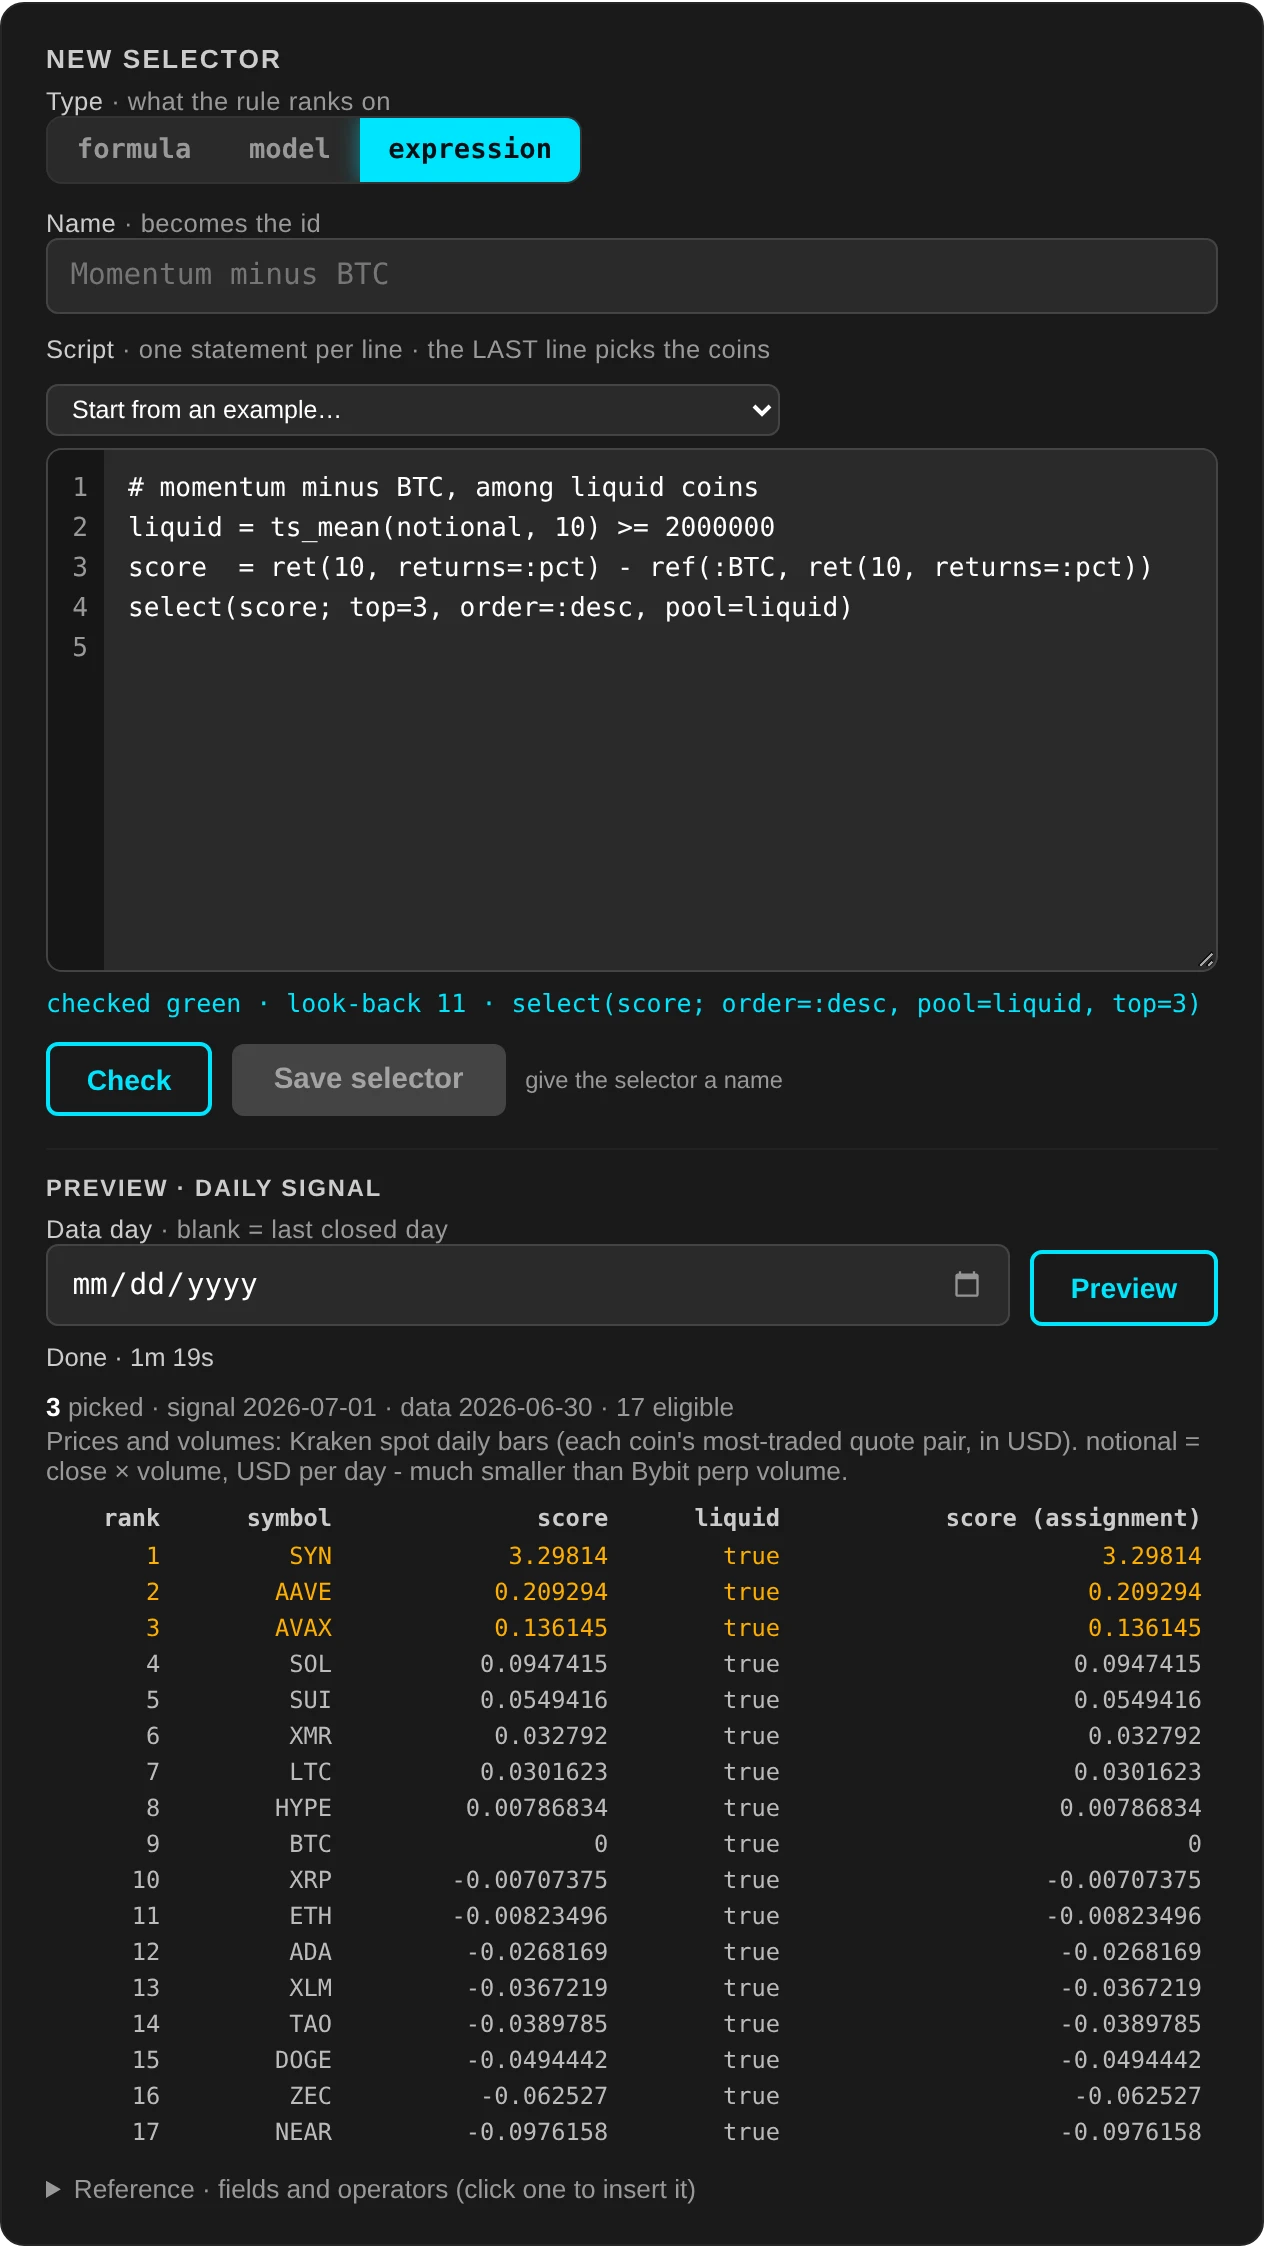
- Rules you set in the form, or a short expression, such as momentum minus BTC's momentum, top 3, among the liquid coins.
- Your own machine-learning model, trained in Python.
- Each selector is checked and previewed day by day: every coin's score and rank on that day, and which ones were picked.
- Selectors are scored on each past day with only the data known that day, so a backtest can follow one over years.
There is no profit split per coin, on purpose: it would invite you to keep the coins that happened to win.
Several portfolios on one account.
Pro and up
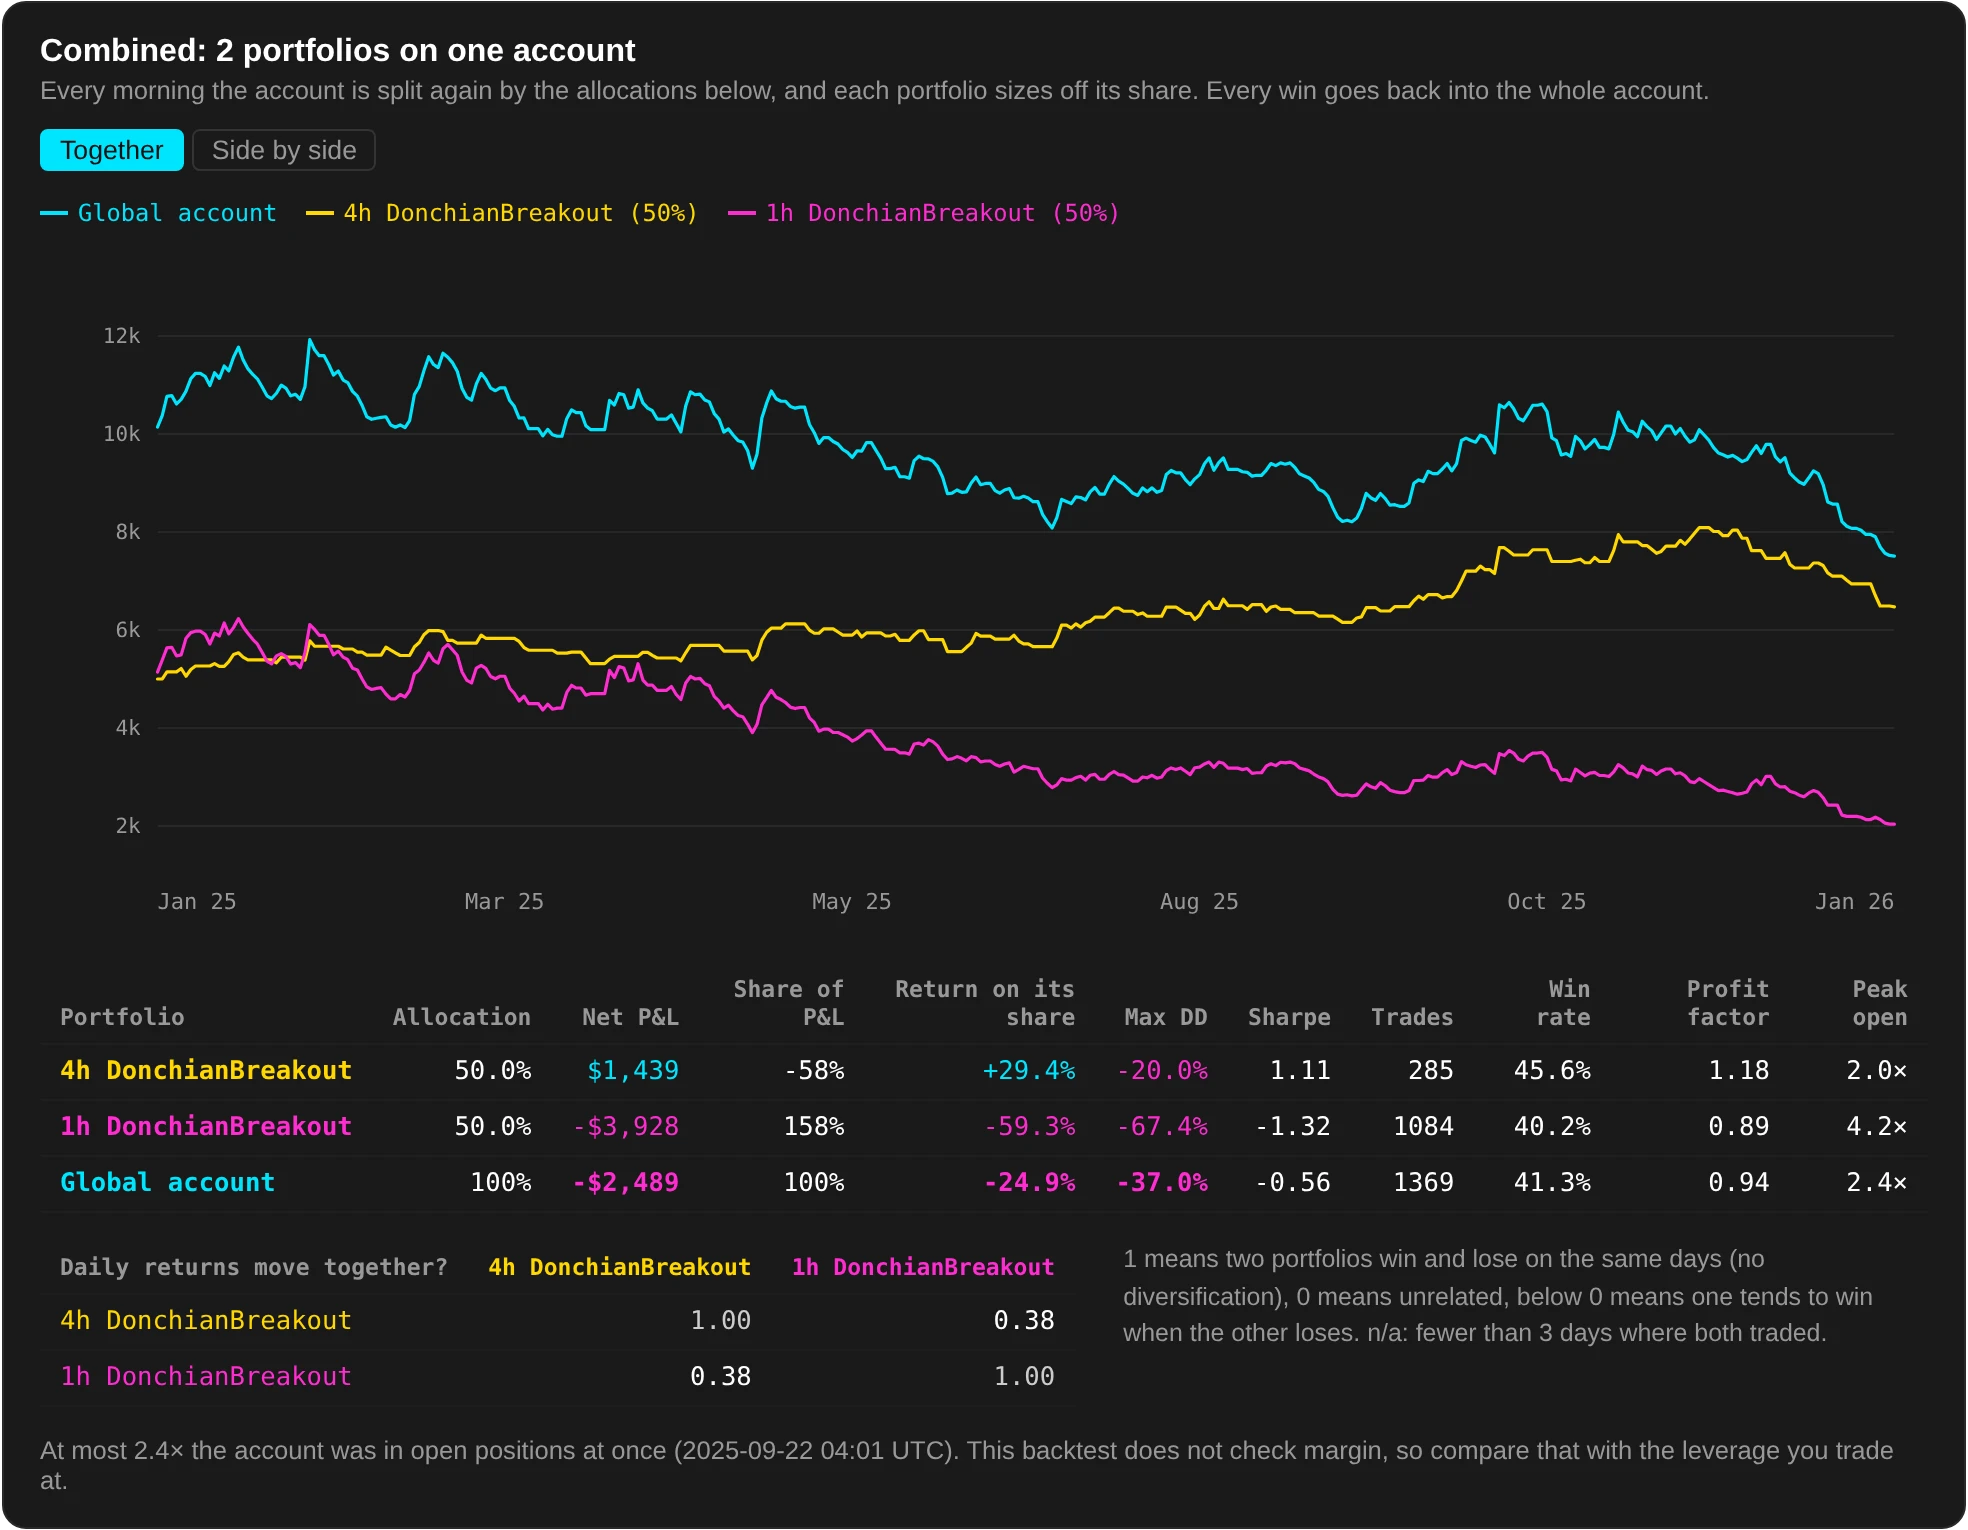
A combined backtest runs up to 8 portfolios on one account, the way they would trade as sub-accounts. Each portfolio is its own sub-account, so you can trade the same coins with different strategies, or the same strategy on different timeframes, at the same time.
- Each portfolio has its own strategy, build, settings, timeframe, selector or coin list, coins per day and positions at once.
- Give each one a share of the account, and a risk per trade as a percent of its share, dollars per trade, or lots.
- Every morning the account is split again by those shares, and the day's profit and loss goes back to the one account, so it compounds the way a real account does.
- The result shows the whole account's curve and each portfolio's curve, together or side by side, how much each portfolio added, how closely their daily returns move together, and the peak exposure.
On paper and live, several portfolios run at once, one per account. On Bybit, each portfolio can trade on its own sub-account under your main account, with a daily rebalancer that makes the real transfers between them.
Does it still work bigger?
Capacity check. Reruns strategies at increasing order sizes, models market impact and shows where performance starts to deteriorate.
The same rigour in backtest and paper.
Backtest fills are simulated with fees, slippage and spread, not optimistic fills. See how backtests are simulated.
Paper trading is a quarantine. A candidate strategy runs on real market data without spending a live account, or even an exchange demo account, until it has earned its way to live. See paper and live.
Compare plans on the pricing page, or follow the install guide.